HouseView_EN_202609 Download the material in pdf format by clicking on the image.

What happened in the last month?
In focus: a resilient US Economy and the rise of Facebook’s AI Agent
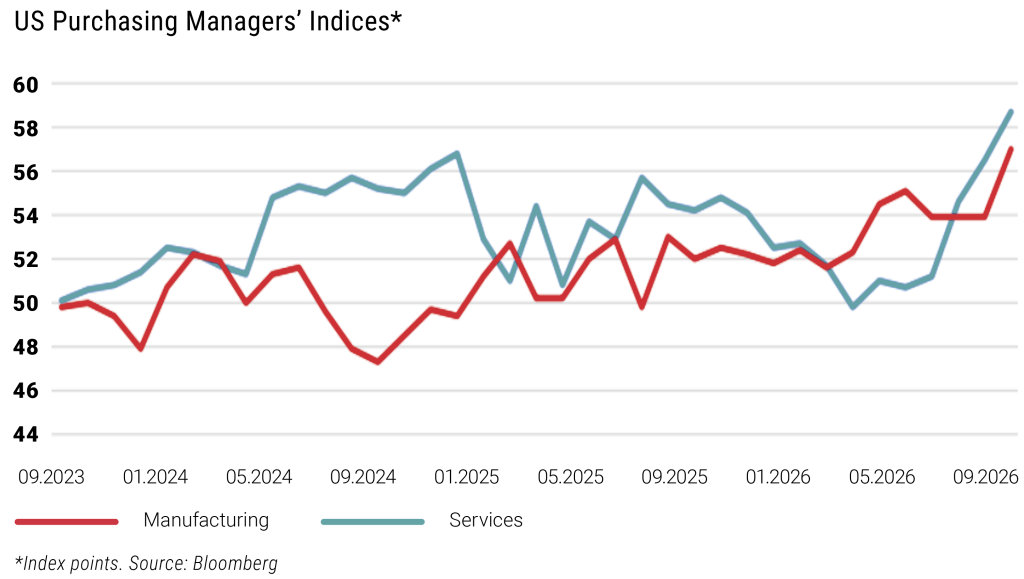
The US economy continues to prove more resilient than expected. According to the latest quarterly figures, real GDP grew at an annualised rate of 2.2%, comfortably above the initial estimate of 1.5%. Growth was driven primarily by surprisingly robust consumer spending and corporate investment in strategic infrastructure and technological development. At the same time, business surveys highlight a sharp divergence in economic activity. The S&P Global US Manufacturing Purchasing Managers’ Index (PMI), which reflects business sentiment, climbed to 57 (readings above 50 indicate expansion). The services PMI stabilised at an even stronger 58.7. Together, these figures point to solid domestic demand. By contrast, the euro area composite PMI remained at 49.2, highlighting the structural challenges facing European industry, the competitive disadvantage created by high energy costs and increasingly cautious European consumers, who are choosing to save rather than spend.
Equity market news
September saw significant sector rotation in equity markets, even as corporate fundamentals remained surprisingly strong overall. According to FactSet, companies in the S&P 500 recorded third-quarter earnings-per-share (EPS) growth of 29.1%, while the price-to-earnings (P/E) ratio stood at a relatively modest 19. Although equities are not cheap, robust earnings growth can help justify current valuations. Investors have begun to question the returns on artificial intelligence investment, prompting substantial flows out of highly valued, capital-intensive technology giants and into more attractively valued sectors with steadier cash generation, including financials, healthcare and communications.
Even so, AI still delivered a major market story. Shares in Meta, Facebook’s parent company, rose by nearly 30% in the weeks following the 8 September launch of Muse, its personal AI assistant. The AI agent can carry out tasks independently, including booking travel, making purchases and sending emails. It may also earn commissions on paid transactions, opening up the prospect of substantial new revenue streams.
Bond market news
Global bond markets experienced a sharp rise in interest rates and yields in September, driven by mounting inflation concerns, increased government bond issuance to finance fiscal deficits and expectations that central bank rates would remain elevated. The US Federal Reserve raised its policy rate by 25 basis points to a range of 3.75–4.00%. Despite stagnating economic activity in Europe, the European Central Bank (ECB) lifted its key rate to 2.50%, while the Bank of Japan (BoJ) increased its policy rate to 1.25%. The impact was immediate: the yield on the 10-year US Treasury reached 5.33%, its highest level since 2002, while the 30-year yield rose to 5.67%. In Europe, the yield on the 10-year UK gilt peaked at 5.35%, showing that these concerns extend well beyond the US. Hungarian forint bonds offer only a modest yield premium. Nevertheless, the real yield available on the benchmark 10-year Hungarian government bond, yielding around 5.8%, remains high enough by international standards to retain and attract foreign capital.
Alternative investments news
Brent crude, the main oil benchmark in Europe, jumped by 14% over the month to trade between USD 103.73 and USD 107.00 per barrel. The rise was driven mainly by the deepening geopolitical crisis in the Middle East and wartime disruption to key maritime shipping routes. US West Texas Intermediate (WTI) crude also became more expensive. Meanwhile, European wholesale natural gas prices peaked at EUR 85/MWh amid concerns about storage levels ahead of the end of the winter stock-building season and capacity constraints in liquefied natural gas (LNG) infrastructure. This represents an increase of almost 100% in just six months. Among precious metals, gold and silver consolidated after their substantial summer rally. Following an August peak of nearly USD 4,700 per troy ounce (one ounce equals 31.1 grams), gold stabilised at around USD 4,200 per ounce. Although central banks buy more than 1,000 tonnes of gold annually – the Dutch central bank’s repatriation of more than a quarter of the country’s 345-tonne gold reserve illustrates its strategic importance – rising interest rates reduce the appeal of precious metals, which pay neither interest nor dividends.
What can we expect in the coming period?
Investment clock
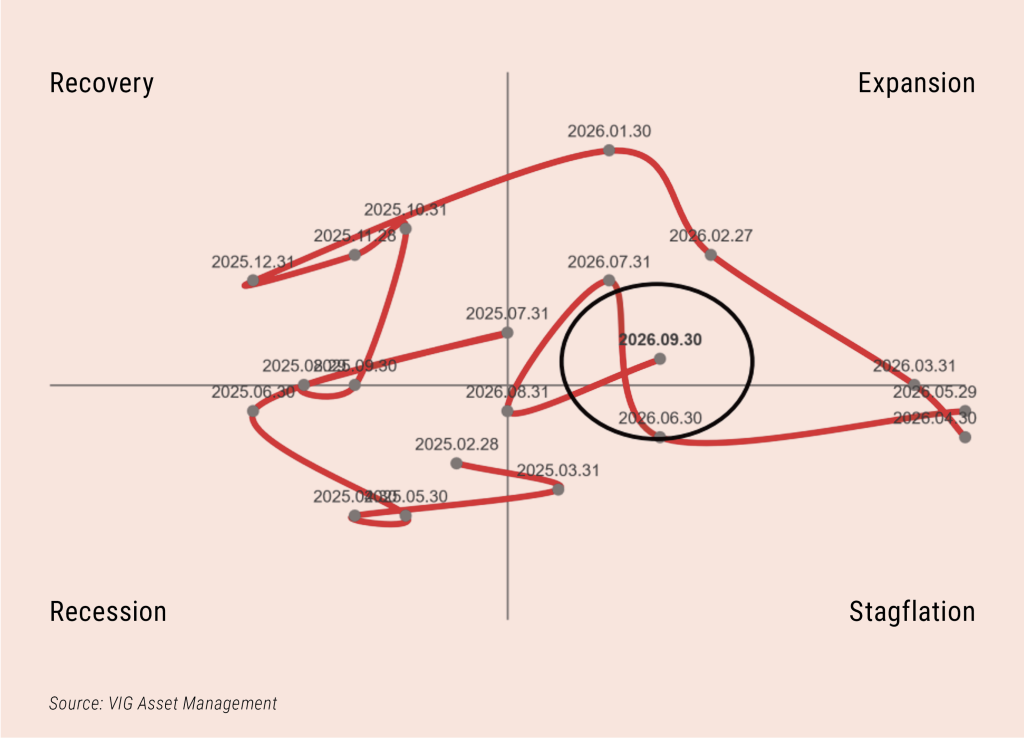
The VIG Global Investment Clock uses economic indicators to assess where we are in the economic cycle and what may come next. Its latest readings suggest a mixed outlook for the coming months, with the US, Europe and China each at a different stage of the cycle. In the US, the indicator has moved from a neutral stagflationary position into the expansion phase, characterised by stronger growth and higher inflation. The European Union, meanwhile, has entered the overheating phase following slightly better growth data. AI-related investment in the US remains the main driver of improving growth figures and economic activity. However, substantial volatility in oil prices adds uncertainty to the leading indicators. The Investment Clock’s recent movements illustrate just how uncertain and fast-changing the macroeconomic environment has become.
Tactical Asset Allocation
In September, we adopted a more cautious, risk-aware approach to tactical asset allocation, while maintaining active, conviction-led positioning in selected areas. This resulted in significant changes both across global asset classes and within individual model portfolios.
Wall Street in focus
The outlook for US equities remains favourable. Analysts expect exceptionally strong earnings-per-share growth of more than 20% during the upcoming US corporate reporting season. In our view, expectations of this magnitude make it unwise to position against market momentum. US economic growth is being driven to a considerable extent by investment in artificial intelligence (AI), while mega-cap technology and communications companies remain the market’s key pillars and growth engines. New AI developments, including Meta’s AI agent and the latest models entering the market, continue to create fresh opportunities for growth in the sector. Company-specific catalysts are also at play, such as the anticipated initial public offering (IPO) of Anthropic, the developer of Claude AI. Major market participants have a vested interest in maintaining favourable equity-market sentiment ahead of such an event.
US bond yields reach multi-decade highs
US Treasury yields rose sharply as higher oil prices and US macroeconomic data pointing to further economic acceleration pushed up inflation expectations. In September, the Federal Reserve raised interest rates by 25 basis points and signalled that further increases could follow. As a result, yields on long-dated government bonds climbed to levels not seen in decades. Higher yields, however, mean lower bond prices. These multi-decade yield highs could therefore offer an attractive entry point into developed-market bonds. Investors may benefit both from today’s elevated coupon income and from potential capital gains if interest rates are cut at a later stage.
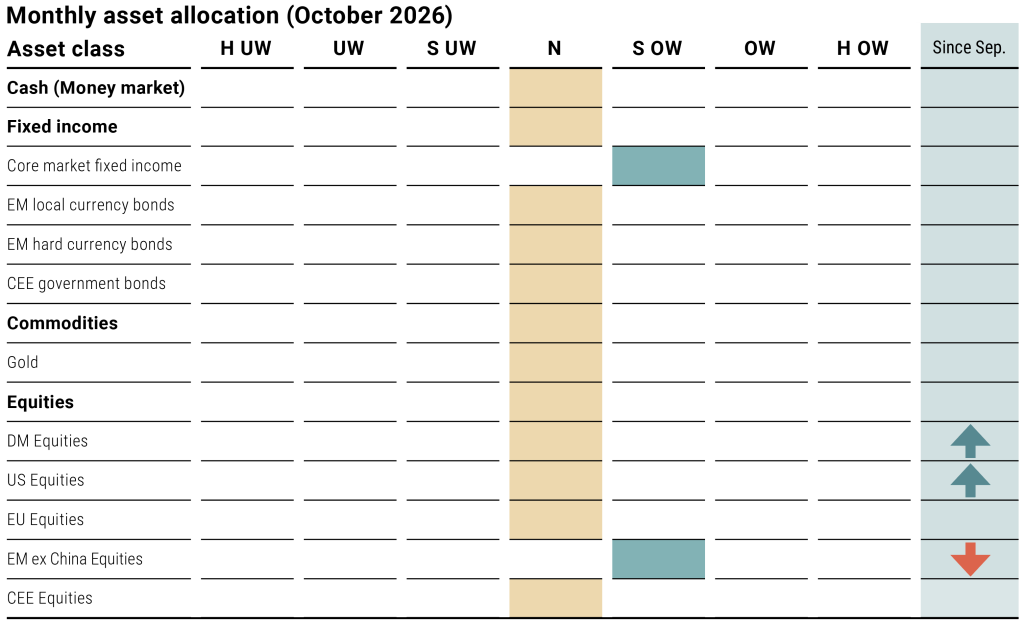
Source: VIG Asset Management
The weights indicate the evaluation of the respective country, region, and asset class, providing a basis for portfolio managers in structuring portfolios and establishing positions, thus helping to capitalize on market opportunities.
Weights:
- Strongly underweight
- Underweight
- Slightly underweight
- Neutral
- Slightly overweight
- Overweight
- Strongly overweight
Changes – change compare to the the previous month
The table was prepared based on our investment clock and quadrant modell**.
Focus fund: VIG Developed Market Government Bond Investment Fund
The Fund, which invests primarily in US, euro area and UK government bonds, offers a compelling tactical opportunity in the current market environment. Following one of the largest bond bear markets on record, US and other developed-market government bond yields have reached levels not seen since 2002. At current yields, government bonds generally regarded as low-risk offer real returns of 2–3%, creating an attractive value-based entry point. Higher yields also mean that coupon income can provide a meaningful cushion within a portfolio: even if yields rise further, potentially to 6%, the interest earned could offset losses caused by falling bond prices. Markets have already priced in considerable negative news and expectations of further monetary tightening, so exceptionally pessimistic investor sentiment may act as a contrarian indicator. Our portfolio managers believe there is a meaningful chance of a correction from oversold levels, with yields declining and bond prices recovering. Against a backdrop of a stronger US dollar and the possibility of an equity-market correction, developed-market government bonds could offer some of the strongest defensive characteristics within the bond universe.
Based on our expectations (based on tactical asset allocation), the fund of the month may outperform in the near future.
VIG Developed Market Government Bond Investment Fund
ESG theme of the month:
A Historic Rapprochement Between the EU and Canada – What Could It Mean from an ESG Perspective?
In her State of the Union speech in mid-September, European Commission President Ursula von der Leyen made a noteworthy announcement: she proposed that Canada become the European Union’s first associate member, an initiative welcomed by Canadian Prime Minister Mark Carney.
This unprecedented proposal comes against the backdrop of the United States’ unpredictable tariff policies and an increasingly uncertain geopolitical environment. In response, the EU is seeking to strengthen ties with countries with which it has already established significant economic relationships. Meanwhile, relations between Canada and the United States have deteriorated considerably, partly fuelled by President Donald Trump’s suggestion that Canada could become the 51st US state. With approximately 70% of Canadian exports destined for the US market, Canada is actively exploring opportunities to reduce its economic dependence on its southern neighbour.
Potential ESG Implications of Associate Membership
Although considerable uncertainty remains surrounding the prospect of Canadian associate membership, further details regarding the direction of cooperation are expected to emerge following the EU–Canada Summit, scheduled to take place in Montreal on 29–30 October.
Nevertheless, it is worth examining the potential areas of cooperation identified so far and considering how they could influence environmental, social and governance (ESG) factors.
Environmental (E): Critical Raw Materials and Supply Chain Resilience
In his address to the European Parliament, Mark Carney identified critical minerals as a key area for potential cooperation between the EU and Canada. But what could this mean in practice?
The two parties established a strategic partnership on raw materials back in 2021, meaning that cooperation in this field is already underway. However, climate change and evolving geopolitical dynamics have created a compelling case for reassessing and potentially elevating this partnership to a new level.
Canada produces a range of minerals and metals that the EU considers strategically critical, including lithium, graphite, nickel, cobalt, copper and rare earth elements. The EU relies heavily on imports from resource-rich countries such as Canada to secure access to these essential materials. For Canada, the EU therefore represents both an attractive export market and an important investment destination.
Beyond the mutual economic benefits of this cooperation, closer ties under a potential associate membership framework could also help reduce operational risks for portfolio companies, particularly battery manufacturers and renewable energy businesses whose operations depend on reliable access to critical raw materials.
Social (S): Human Rights and Stability
Social responsibility is another essential consideration in sustainable investing. A closer partnership between the EU and Canada could provide ESG-focused investment funds with a more stable framework for managing social risks.
The growing alignment between the EU and Canada is rooted in shared democratic values and a mutual commitment to human dignity. Canada’s mining sector is notable for its stringent consultation requirements concerning the rights of Indigenous peoples.
Against this backdrop, portfolio companies held by ESG-focused and sustainable investment funds could benefit from sourcing raw materials from jurisdictions where respect for human rights receives particular attention. For renewable energy and battery manufacturers, such sourcing practices could help mitigate supply chain-related social risks and strengthen the long-term sustainability of their operations.
Governance (G): Research Cooperation and Transparency
Should Canada become the EU’s first associate member, the partnership could also facilitate progress in several areas relevant to governance.
In his speech to the European Parliament, Canadian Prime Minister Mark Carney expressed his country’s interest in joining the EU’s Erasmus+ programme, which provides funding for initiatives supporting international education, training and professional mobility.
Such cooperation could pave the way for greater alignment in educational and research standards, as well as improved mutual recognition of qualifications and research data. It could also enhance institutional transparency and expand opportunities for cross-border collaboration.
From an investor’s perspective, these developments could contribute to a more transparent and traceable innovation ecosystem, alongside greater predictability in intellectual property protection within joint research and development (R&D) projects.
Strategic Outlook and Market Implications
Overall, Canada’s potential associate membership could represent considerably more than a conventional trade agreement. It could lay the foundations for a stable strategic alliance, offering greater resilience amid the current geopolitical uncertainty.
From an investment perspective, closer EU–Canada cooperation could generate meaningful benefits across all three ESG pillars. Canadian raw materials sourced under stringent environmental (E) and social (S) standards could enhance supply chain security for companies operating in the green economy, while joint initiatives relating to governance (G) could contribute to a more transparent and predictable market environment.
Against this backdrop, developments surrounding the upcoming EU–Canada Summit will be particularly worth monitoring.
This is a distribution announcement. Detailed information is needed to make a well-founded investment decision. Please inform yourself thoroughly regarding the Fund’s investment policy, potential investment risks and distribution in the Fund’s key investment information, official prospectus and management regulations available at the Fund’s distribution outlets and on the website of VIG Asset Management Hungary Closed Company Limited by Shares (hereinafter: Asset Management) (vigam.hu). The costs related to the distribution of the fund (buying, holding, selling) can be found in the fund’s management regulations and at the distribution outlets. Past returns do not predict future performance. Please note that in comparison with other investment funds, the return achieved may be affected by differences in the reference index and therefore the investment policy.
The future performance that can be achieved by investing may be subject to tax, and the tax and duty information relating to specific financial instruments and transactions can only be accurately assessed on the basis of the individual circumstances of each investor and may change in the future. It is the responsibility of the investor to inform himself about the tax liability and to make the decision within the limits of the law.
The information contained in this leaflet is for informational purposes only and does not constitute an investment recommendation, an offer or investment advice. Asset Management accepts no liability for any investment decision made on the basis of this information and its consequences.
This leaflet may contain trade names or brand names owned by third parties, the use of which serves illustration purposes only. All product and company names are trademarks™ or registered trademarks® of their respective owners. The use of such trademarks does not imply any business or other relationship between Asset Management and the owners of the trademarks, nor shall it be interpreted as a recommendation by Asset Management.
The Asset Management’s license number for managing alternative investment funds (AIFM) is: H-EN-III-6/2015. The Asset Management’s license number for UCITS fund management (collective portfolio management) is: H-EN-III-101/2016.